
U Microfinance Bank launches its first impact assessment and baseline study and shares new insights about their microfinance customers.
Islamabad:
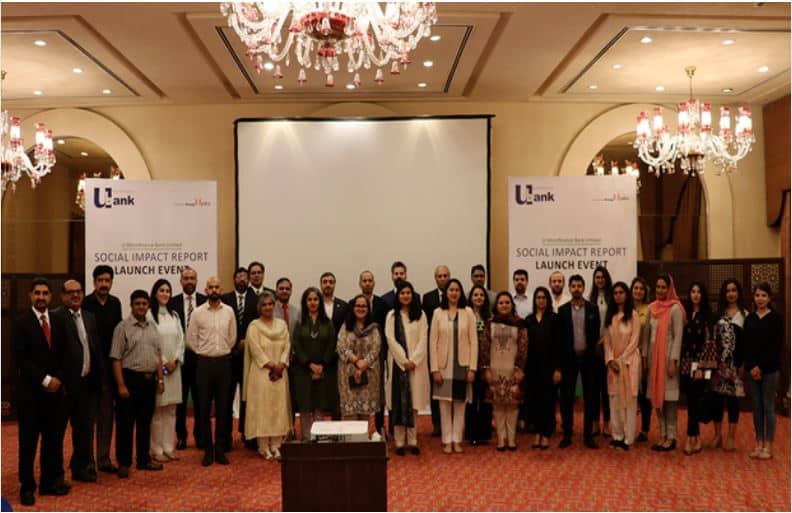
U Microfinance Bank launched its flagship Impact Measurement & Baseline report today in an event hosted in Islamabad. The guests included executives from various microfinance, research and international institutions who all came together to discuss the challenges and opportunities in measuring social impact within the Pakistani microfinance sector. This first-of-its-kind report in the Pakistani ecosystem, is a concrete step forward by U Bank to gather and open-up more customer side data and insights and ensure better product and service design with the aim of improving the sectors social impact outcomes.
The report comes at an opportune time when the global microfinance industry is grappling with the key question of its ability to deliver on its dual promise of social and economic performance. While recent research has put the core assumption of the sector, that it lifts people out of poverty, under increasing scrutiny with evidence contrary to that belief remains in agreement that it is still a major part of the equation.
The report looks at data across five main categories of impact – household, livelihood, health and nutrition, business and the bank’s product and service quality. The first report, which will be a biennial effort, establishes a baseline of where U Bank’s customers are currently against these metrics and analyzes their perceptions about the impact that the microfinance loans have had on their lives and livelihood. The methodology used is a blended approach – combining elements of experimental and Acumen’s lean data approaches – to put forth a new way of measuring impact from the costly and time and labor intensive RCTs that have been traditionally been favored to assess impact. In line with global research, our data shows that microfinance plays a key role in helping our customers overcome shocks such as illness, death, crop failures and natural disasters. Furthermore, one of the biggest values our customer attribute towards the loan is the resulting gains in quality of life and how it helps smooth household consumption. 75% of the respondents indicated that the loan has led to a positive impact on their business income and a majority of them agreed that the loan was critical for the health and quality of their businesses. The report also digs deeper into the data-set and